Car Insurance Total Loss in 2026: How Settlement Value Is Calculated
When an insurer declares a car a total loss, the hardest question is often how much money the owner will receive. The value may not match the loan balance or the price of a similar replacement. This guide explains settlement calculations, evidence and next steps for drivers worldwide. Local insurance rules and policy wording always control the final result.
What total loss means
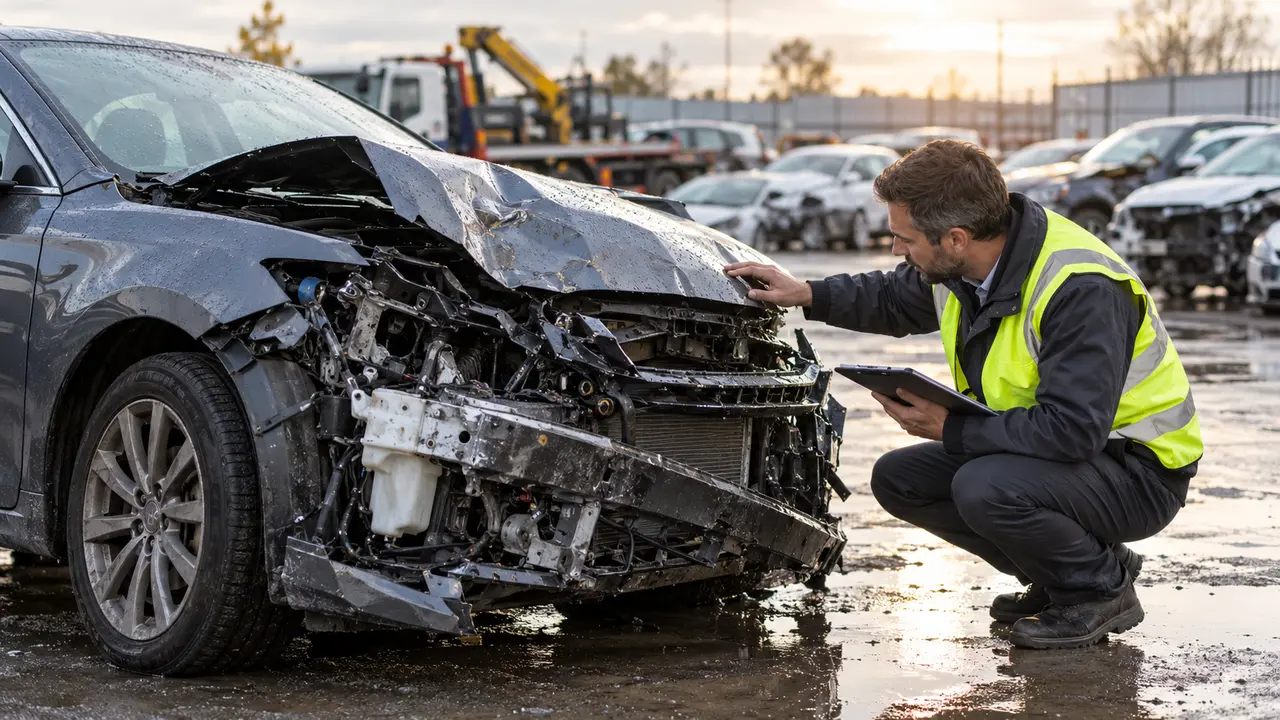
An insurer may call a car a total loss when the damage is too costly to repair under its rules or when the vehicle cannot be restored safely. Some countries use a percentage of value, while others use an economic or safety assessment. A car can look repairable to an owner yet still be written off after hidden damage and repair costs are counted. Ask for the specific policy and local legal basis for the decision. Total loss is not the same as a vehicle simply refusing to start.
How insurers estimate value
Many policies pay an actual cash value or market-based amount, subject to the contract. Others use agreed value, invoice protection or replacement benefits. The insurer may consider age, mileage, condition, options and comparable local sales. Request the valuation report and check that the exact model, trim and equipment are correct. A missing option or wrong mileage can change the amount. The National Association of Insurance Commissioners explains common auto settlement concepts for consumers. Your market may use different terms and formulas.
The deductible still matters
If you claim under own-damage cover, a deductible or excess may be subtracted from the settlement. Additional fees, taxes or salvage treatment can also affect the final amount. Ask for an itemized calculation showing starting value, adjustments and deductions. Do not compare a headline value with the amount reaching your bank without reading the details. If another driver is at fault, recovery rules may differ. The insurer should explain which policy section pays and whether your deductible can later be reimbursed.
Check the net payment
Ask the insurer to show the market value or agreed amount, deductible, salvage adjustment and any other charge separately.
Finance does not disappear
A car may be worth less than its outstanding loan. If the insurer pays market value, you could still owe the lender money after the car is gone. Some buyers have gap protection that covers eligible shortfalls, but terms and exclusions vary. Contact the lender for a current settlement amount and ask the insurer how payment will be directed. Do not stop loan payments until the lender confirms the balance is cleared. A total-loss claim and a finance contract are separate obligations that need coordination.
Check comparable vehicles
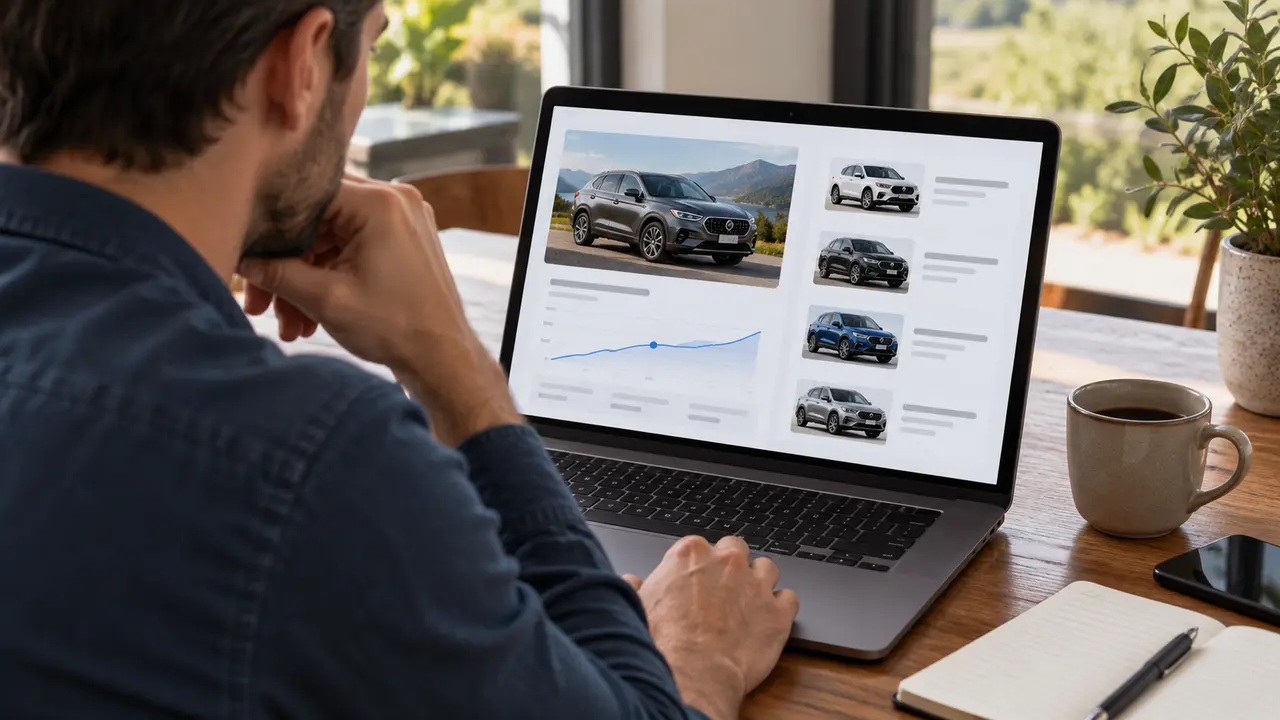
Find genuine local listings for the same year, variant, mileage and condition. Ask whether the insurer used vehicles in your area and made fair adjustments for options or recent condition. Listings are not completed sales, so do not assume the highest asking price is your entitlement. But clear evidence of a wrong trim or missing equipment can support a correction. Record screenshots with dates and details. Present a short, factual comparison rather than sending dozens of unrelated luxury models.
Document vehicle condition
Service records, recent tyres and maintenance bills can help show the car’s condition before the loss. They do not automatically add their full cost to market value. A new set of tyres may support a condition adjustment, while an expensive accessory might need separate cover. Provide photographs from before the accident if available. Keep repair invoices and warranty work. Do not alter documents or exaggerate the car’s state. Credible evidence is more likely to help than a claim that every maintenance expense should be refunded.
What happens to the damaged car
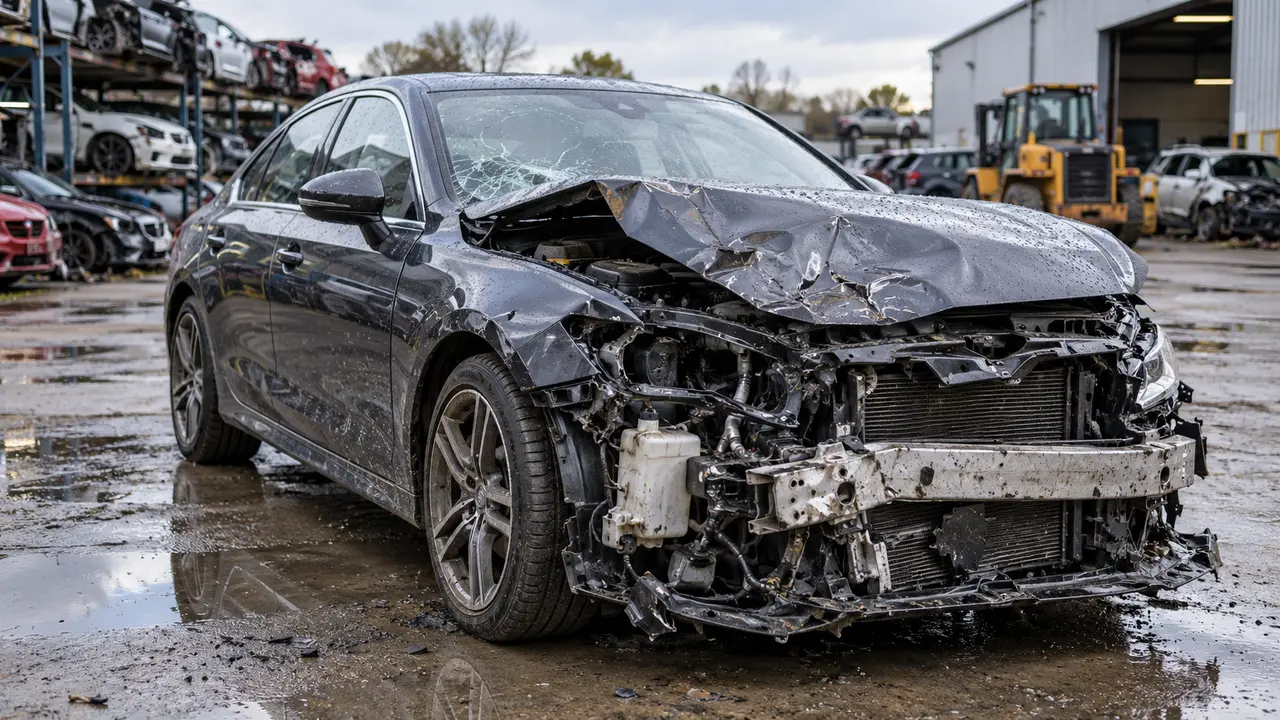
After settlement, the insurer may take ownership of the salvage or allow you to retain it under certain conditions. Keeping a written-off car may reduce the payout and can trigger strict inspection, registration and disclosure rules. Never assume you can simply repair and drive it. Check local law and insurance eligibility before agreeing. If you keep the vehicle, understand storage, towing and disposal responsibilities. A cheap salvage deal can create substantial legal and safety costs.
The right to review a valuation
If you believe the settlement is wrong, ask for a written explanation and the insurer’s review or appraisal process. Point to specific errors such as an incorrect model, mileage, equipment or comparison market. Some policies have independent appraisal clauses; local regulators may offer complaint processes. Do not ignore response deadlines. Keep conversations calm and make requests in writing. A dispute about value is easier to resolve when both sides can see the same documents and calculation.
Focus on errors, not feelings
A wrong trim, odometer reading or missing equipment is specific evidence. The fact that a car was loved does not itself change market value.
Rental car and transport costs
While the claim is being handled, you may need another way to travel. Some policies include temporary vehicle or transport reimbursement, but benefits often have daily and total limits. Ask when the benefit ends, especially after a total-loss offer is made. Do not assume a hire car will remain covered until you purchase a replacement. Keep transport receipts where required. A clear timeline can help avoid personal charges that appear after the main settlement seems complete.
A realistic settlement example
Imagine a car with a pre-loss market value assessed at 12,000 local currency units, a 500 deductible and an outstanding loan of 13,000. The insurer’s payment may be 11,500 under the simplified policy example, leaving a finance shortfall. The driver checks whether separate gap cover applies and confirms the lender payoff. Real claims may include other adjustments and local rules. The example shows why vehicle value, deductible and debt should be reviewed together rather than as separate surprises.
Choose the replacement wisely
A total-loss payout may be less than the cost of an equivalent new car. Before shopping, determine the net money available after loan settlement, taxes and any expenses. Compare used options and financing carefully. Do not rush into a long loan simply because you need transport. Ask whether existing insurance can transfer to the replacement and when it starts. A separate budget keeps the stressful claim from turning into a second financial problem.
Check the payout timeline
Ask when the insurer expects to issue payment after you accept an offer and which documents or title transfers must happen first. If a lender has an interest in the car, clarify which amount goes to the lender and when any remainder comes to you. Keep proof of the transaction and do not spend money you have not yet received. Delays can matter when you need replacement transport or must keep making loan payments. A written timeline helps avoid confusion.
Keep a clear claim file
Save the claim number, incident report, valuation, settlement offer, finance payoff, salvage instructions and final payment record. Note calls and deadlines. Ask for confirmation when title transfer and loan settlement are complete. If the vehicle carries connected services, remove your personal account access as the insurer or owner process allows. Keep copies of any appeal or complaint. A well-organized file reduces confusion when several organizations handle the same car.
Frequently asked questions
Does total loss mean the car cannot be repaired?
Not always. Economic write-off rules can apply even when repairs are technically possible. Safe reuse depends on local law and inspection.
Will the insurer pay my full loan?
Not necessarily. Market value and outstanding finance can differ. Check separate gap protection if you have it.
Can I challenge the valuation?
Ask for the report and correct factual errors using comparable vehicles and records, following the policy review process.
Bottom line: Request an itemized valuation and coordinate settlement, finance and salvage before signing.